← The Global Intelligence Brief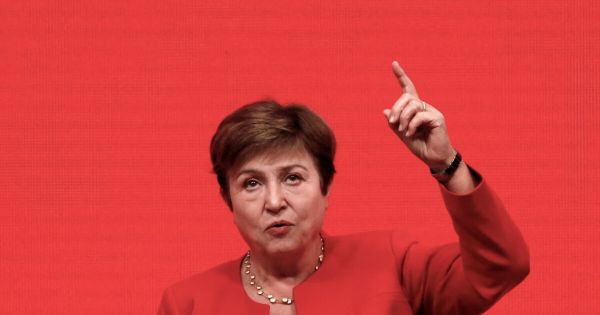
Morning Edition · Thursday, November 19, 2026Published at 12:14 AM EST · New York
IMF Says Global Public Debt Will Soon Reach 100% of World Output, the Highest Level Since World War II
A day earlier, the European Central Bank's financial stability review named weak public finances and AI valuations as the main risks to markets in the euro area.
Kristalina Georgieva, managing director of the International Monetary Fund (IMF), told the APEC summit in Shenzhen on Thursday that global public debt will soon reach 100% of world gross domestic product (GDP), the highest level since World War II. She called for "urgent attention" to government finances. In the same session, she urged countries to prepare their digital infrastructure and labor markets for AI.
The European Central Bank (ECB) delivered a similar warning a day earlier. Its November Financial Stability Review lists risks from AI valuations, fiscal imbalances and geoeconomic tensions. Boris Vujčić, the ECB vice-president, said before publication that a reassessment of the AI narrative "may trigger an abrupt repricing in markets," Euronews reported. He also noted that debt issuance by cloud and AI-infrastructure firms has reached record highs this year. On public finances, the ECB said that some euro-area governments carry high debt while long-term borrowing costs are already rising, and that investors could suddenly demand much higher yields. Vujčić said the main response must come from fiscal policy. The ECB also wants limits on hedge-fund leverage.
The ECB's leadership is changing at the same time. The Economist profiles a new executive group of "a Spaniard, a German and a Frenchwoman." This team will decide whether the bank buys bonds to cap a country's yields if investors demand much more to lend to it.
Both institutions face the same constraint. Neither can cut public debt itself. A central bank can only decide how much of that debt it will hold.
Part of a tracked trend
The Long-End Revolt
Governments will keep reaching for balance-sheet tools to suppress long-term yields, and bond markets will keep repricing duration higher anyway, so each intervention transfers demand into scarce assets instead of lowering borrowing costs.
Townsquare
Start a discussion in Townsquare.
More from this edition
- Federal Reserve Minutes Show Almost All Officials Expect More Rate Increases, Pushing Gold to a 14-Month Low
- Anthropic Prices Initial Public Offering at $83 a Share, Raising $107.3 Billion Including a Placement Bought by Its Own Suppliers
- Putin and Trump Open Talks in Shenzhen Before the First Three-Way Summit With Xi
- Putin Rules Out Energy and Black Sea Truce After Third Strike on Crimean Bridge, Vows "Far More Painful" Response
- Oil Holds Near $82 as a Report That Trump Is Weighing More Iran Strikes Offsets Forecasts of a Supply Surplus
- Bitcoin Falls Near $62,500 With Gold, and a Miner That Sold Its Last Coins Warns It May Not Fund an AI Data Center
- Putin Tells APEC That Sanctions Are a Thing of the Past, and Canada's Carney Says Sanctions Must Stay Until the War Ends
Comments
0No comments yet.