← The Global Intelligence Brief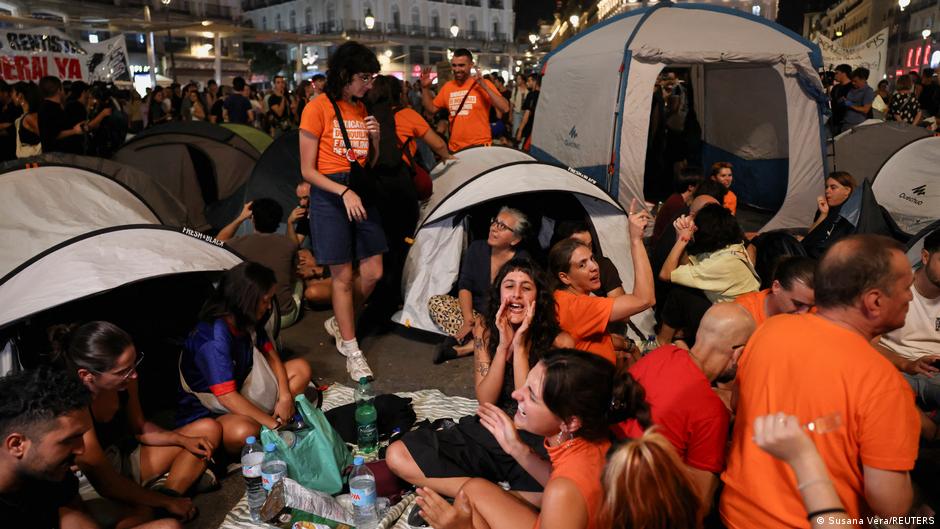


 3 sources
Morning Edition · Sunday, September 27, 2026Published at 1:23 AM EDT · New York
Housing Costs Turn Into Electoral Risk From Madrid to the American Midterms
Tens of thousands marched in the Spanish capital after the eviction of an 87-year-old woman, while institutional landlords have become a target in United States midterm campaigns.
Tens of thousands of people marched in Madrid this weekend after the eviction of Maricarmen Abascal, an 87-year-old woman whose removal from her home became a national story. Protesters demanded measures to curb rising costs and reduce evictions, and Al Jazeera reported the same demonstrations as a demand for answers from the government.
In the United States, similar political pressure over housing costs is building, aimed at a different target. Financial Times analysis found that institutional investors are being blamed for rising housing costs and have become a campaign issue ahead of the midterm elections, with private equity landlords named directly by candidates in both parties.
Israel shows the same affordability problem producing a different market symptom. With sales stalled, developers are working through consumer clubs that offer double-digit discounts, and Globes reported that one such campaign sold 72 apartments in three days using discounts, flexible payment terms and exemption from index linkage. The same terms have become standard across the market without reviving it.
The common cause is monetary. A decade of suppressed interest rates inflated the capital value of housing, then the rate reversal raised the cost of carrying it without reducing prices to match incomes. Owners hold, buyers cannot enter, and governments face pressure to act on the symptom.
Veracity: Corroborated
80/100- If true, who benefits
Tenant unions and incumbent governments gain from visible pro-renter measures before elections in Spain and the United States, while listed residential landlords and private equity housing funds carry the regulatory cost, and existing owners keep the capital gains that neither intervention reverses.
- The nuance
The Madrid march and the eviction of Maricarmen Abascal are well documented, though turnout is disputed (about 25,000 by official count against more than 300,000 claimed by the organisers), and the American framing understates that institutional investors hold roughly 3 percent of single-family rentals, so blaming them for the price level substitutes a political target for a supply constraint.
An open-source-intelligence read of how likely this story is true with its real nuance, not a judgment of any outlet. It assesses the claim, weighing independent and adversarial reporting. How we label confidence.
What this means
The mechanism runs from monetary policy to asset prices to politics. Years of low rates capitalised into land and housing values, and the subsequent rise in rates raised mortgage and development financing costs without a matching fall in prices, which locks out new buyers and concentrates ownership among cash and institutional holders. The exposed parties are listed residential landlords and private equity housing funds facing rent caps, transaction taxes or ownership restrictions, homebuilders in markets where discounting has become standard, and banks holding mortgage books originated at peak valuations. Politicians in Spain and the United States want visible action before elections and can most easily deliver rules aimed at landlords, which is the intervention that addresses distribution rather than supply. The precedent is Berlin's 2020 rent freeze, which courts struck down in 2021 after new construction slowed. The likelier outcome over the coming months is a wave of landlord-targeted measures in Spain and in US state legislatures, which will compress rental yields without adding units. A serious loosening of construction and permitting rules would be the sign that governments are treating the supply constraint instead.
Synthesized from: Deutsche Welle · Financial Times · Globes
Townsquare
Start a discussion in Townsquare.
More from this edition
- Iran Says It Captured a Second US Underwater Drone in Hormuz as Trump Rejects Reopening Plan
- Long-Dated Treasury Yields Reach Multi-Decade Highs as Equities Still Close the Week Up
- Gold Sits About 23 Percent Below Its January Peak While Bitcoin Rallies With Equities
- Saudi Coalition Intercepts Missiles and Drones Aimed at Riyadh and Khamis Mushait
- Trump Says Xi 'Understands' His Taiwan Position as Beijing Presses for a US Statement Against Independence
- Kenya, Indonesia and Greenland Show Minerals and Rail Becoming Instruments of Bloc Competition
- Investment-Grade Diamond Prices Fall to Their Lowest Recorded Level as De Beers Bets on Natural Stones
Comments
0No comments yet.