← The Global Intelligence Brief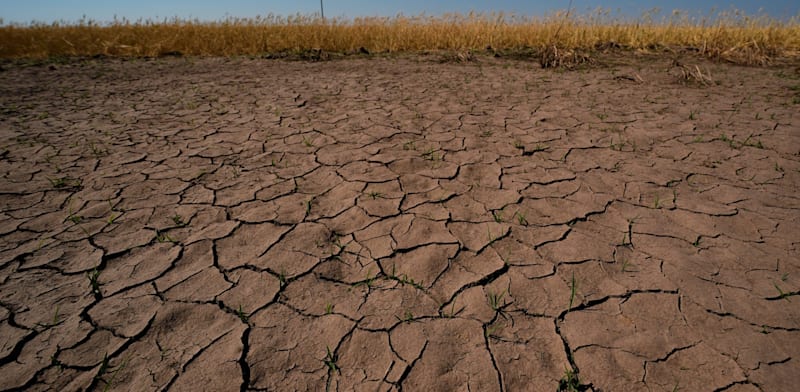


 3 sources
Morning Edition · Thursday, October 1, 2026Published at 1:16 AM EDT · New York
Grain and Sugar Prices Climb as El Niño Meets an Energy Risk Premium
Corn has risen about a third since late June and sugar close to a quarter since late July, with Brent crude near $97 a barrel adding to input costs.
Globes reported that a combination of a strong El Niño event in the Pacific, tension around the Strait of Hormuz and the war in Ukraine has pushed up the prices of wheat, corn and sugar, and that Israeli economists expect domestic food prices to rise once the holiday period ends, with a strong shekel having delayed the effect so far.
The commodity moves are measurable. Corn has gained roughly a third since late June and sugar close to a quarter since late July, according to market data cited by Globes. CNBC reported that sugar has outperformed the equity market this year, driven by weaker European beet yields, reduced Brazilian output and El Niño-related disruption to cane in Thailand and India. Wheat has been less consistent, with Chicago futures falling in the week to 21 September from a high set on 3 September. Forecasters at the United States National Oceanic and Atmospheric Administration put a high probability on this event ranking among the strongest since 1950.
Energy is the multiplier. Brent crude traded near $97 a barrel on Wednesday, about 7% higher over the past month, and fuel and fertiliser costs feed directly into the price of every harvest and every shipment. Importing countries with weak currencies pay both increases at once.
Food inflation of this kind is the component central banks claim to look through. Households do not, and neither do the governments that subsidise bread and fuel.
What this means
The mechanism is a supply shock in soft commodities arriving while energy carries a war premium, which raises both the production and the transport cost of food simultaneously. The exposed parties are food importers with weak currencies, notably in North and West Africa and South Asia, where subsidy bills expand and fiscal deficits widen, and food processors whose input hedges roll off into higher prices. Exporters of sugar, grain and fertiliser gain the income. Central banks will treat it as a relative price change rather than a monetary one, which is defensible in theory and politically unsustainable where food is a large share of the consumption basket. The precedent is 2010-2011, when drought-driven grain prices combined with high oil prices and preceded subsidy crises and political unrest across several importing states. The likelier outcome over the next two quarters is rising food-price inflation in import-dependent emerging economies and renewed export restrictions by producers protecting domestic supply, which tighten the world market further. A rapid weakening of the El Niño signal alongside a fall in crude would remove both legs of this read.
What to watch
- New export restrictions or duty changes on rice, wheat and sugar by major producers, since these amplify the original shock for importers.
- The United Nations Food and Agriculture Organization monthly food price index, the broadest single measure of whether this is spreading beyond individual crops.
- Subsidy and fuel-price decisions in large importing countries, where the fiscal cost of absorbing food inflation shows up first.
Observations to monitor, not financial advice.
Synthesized from: Globes (Hebrew) · CNBC · EBC
Townsquare
Start a discussion in Townsquare.
More from this edition
- Long Bonds Keep Falling Even After United States Inflation Cools
- Bitcoin Loses Its Move Above $85,000 as Yields Refuse to Fall
- South Korea's September Exports Reach $120.9 Billion as Chip Sales Triple
- United States Completes Iraq Withdrawal as Tehran Receives Washington's Reply
- Pakistan Strikes Two Sites in Afghanistan, Kabul Says Nine Civilians Killed
- Japan Tightens Residency Rules on the Day Takaichi Promises a Growth Plan
- Cockpit Attack on Dubai-Tel Aviv Flight Prompts Saudi Arrest and Competing Accounts
- Huawei Puts Self-Designed Kirin Chips Across the Mate 90 Line
Comments
0No comments yet.