← The Global Intelligence Brief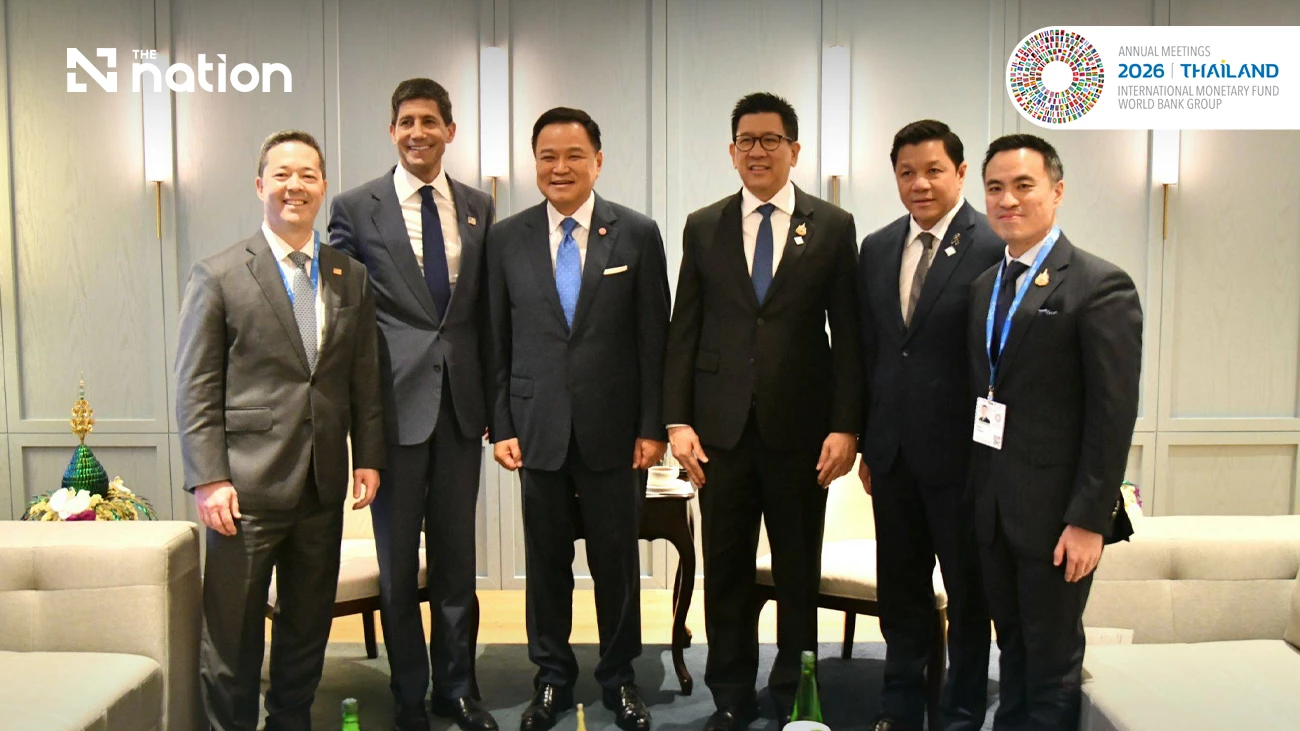


 4 sources
Morning Edition · Saturday, October 17, 2026Published at 1:06 AM EDT · New York
Warsh offers no rate guidance in Bangkok as US inflation reaches 3.7% and the 10-year Treasury yield stays near 5.1%
Traders cut the odds of an October rate hike to about 20% after the Federal Reserve chair's silence, while still pricing a hike by year-end, and in Tokyo, Rakuten paid a 4.37% coupon to sell yen bonds to retail savers.
Kevin Warsh, chair of the Federal Reserve, spoke at the International Monetary Fund (IMF) and World Bank meetings in Bangkok this week. The Nation Thailand reported that he praised the host country's organization of the meetings. He gave no forward guidance on interest rates, and traders cut the probability of a hike at the October meeting to about 20%. The benchmark 10-year Treasury yield ended Friday near 5.085%. For the week, the 30-year yield fell 17 basis points to 5.43% and the 2-year yield settled at 4.72%.
Warsh's silence followed a hot inflation report. The consumer price index (CPI) rose 0.6% in September and 3.7% from a year earlier, and gasoline accounted for more than half of the monthly increase. Core inflation, which excludes food and energy, rose to 2.6% a year earlier from 2.4%. Wholesale prices also rose sharply in September. After the CPI release, futures markets priced the odds of a hike before year-end above 96%. The Fed already raised rates in September, when the 10-year yield returned to 5%.
The rise in borrowing costs is reaching beyond Washington. In Tokyo, Rakuten Group sold a record ¥400 billion of 5.5-year bonds, mostly to retail investors. The bonds carry a 4.37% coupon, priced 200 basis points over the benchmark 10-year Japanese government bond, which implies a government yield near 2.4%. Japanese households now get yen income that was unavailable for most of the past two decades.
The Fed's routine business continued. On the same day it ended enforcement actions against Gardner Bancshares and Small Business Bank.
Part of a tracked trend
Renewed Fed Tightening Fears Rattle Global Markets
Over the next 3-6 months stronger US data revives expectations of Fed rate hikes, driving a firmer dollar, equity selloffs in export-heavy markets, and pressure on hard assets as the IMF warns of recurring economic shocks.
What this means
The Fed is trying to slow a price rise that comes mostly from an oil supply shock. Higher rates do not produce more barrels, so tightening works mainly by squeezing credit-dependent borrowers: unprofitable technology firms, commercial property and leveraged buyers of long bonds. With CPI at 3.7%, a 5.1% 10-year yield is a real return of about 1.4 points. That is enough to keep pressure on asset prices built up during years of cheap money, but not enough to make cash a clearly better store of value than real assets. Warsh's silence is new information. The consensus reads it as dovish, but the more likely reason is that the Fed wants the October inflation data before committing. The 2008 precedent is worth noting: the European Central Bank (ECB) raised rates in July 2008 during an oil price spike and reversed course within months as growth collapsed. The likelier path is one more Fed hike by December, followed by a pause once energy-driven inflation peaks. This read depends on Brent holding above $100. It would be proved wrong by a sharp fall in core inflation or by credit stress forcing the Fed to stop early.
What to watch
- The October payrolls and CPI reports. A second hot core reading would make a December hike the base case and lift the dollar against importer currencies.
- Demand at upcoming long-dated Treasury auctions. Weak bidding would show that buyers want more yield to hold US duration, whatever the Fed signals.
- More Japanese corporate bond sales aimed at retail investors. A run of them would show that Japanese household savings are moving into domestic credit instead of overseas assets.
Observations to monitor, not financial advice.
Synthesized from: The Nation Thailand · The Japan Times (Business) · CNBC · Federal Reserve
Townsquare
Start a discussion in Townsquare.
More from this edition
- Trump waives Russia sanctions law's secondary tariffs two days before they take effect, sparing India and China
- Brent touches $110 for the first time since May after attacks on at least nine ships near the Strait of Hormuz
- Nasdaq falls 2.1% as fears over AI debt and interest rates hit chipmakers and software stocks together
- Gold and bitcoin both trade below year-ago prices as Google quantum advance raises the risk to early bitcoin wallets
- Flávio Bolsonaro promises a fiscal adjustment but will not touch minimum-wage indexation or health spending floors before Brazil's runoff
- Ukrainian drone barrage shuts all four Moscow airports and restricts flights across 22 Russian airports
- Missiles strike Aden airport again as the Houthis widen attacks on Saudi Arabia and the Bab el-Mandeb shipping route
Comments
1Oct 17, 5:06 AM
The 2 year at 4.72% against a 10 year near 5.085% leaves a positive spread of about 37 basis points, so the long end rather than near term hike pricing is setting borrowing costs.