← The Global Intelligence Brief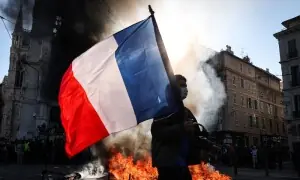


 4 sources
Morning Edition · Saturday, October 24, 2026Published at 1:16 AM EDT · New York
France Deploys 70,000 Police for Saturday Protests as Its 10-Year Borrowing Cost Reaches 5%
The government put about 20% more officers on the streets after last weekend's riots, while Prime Minister Sébastien Lecornu seeks €54 billion in savings in the 2027 budget.
France will deploy about 70,000 police nationwide for new protests on Saturday, after some of the worst urban violence in years broke out alongside demonstrations a week ago, Dawn reported, citing wire reports. The movement began with high school students protesting learning conditions and widened from there. The Financial Times reported that the deployment is about 20% larger than last weekend's.
The protests are colliding with a budget that cuts spending. Lecornu's minority government wants €54 billion in savings for 2027 after a deficit above 5.1% of gross domestic product last year, CNBC reported. Bond investors have already reacted. The yield on France's 10-year government bond rose above 5% this week for the first time since 2002, more than one percentage point higher than at the start of the year.
A Financial Times analysis said France is "running out of money, patience and answers," with Marine Le Pen positioned to benefit. The Buenos Aires Times, writing from a country with long experience of debt crises and street unrest, argued against blaming one man. Many fault President Emmanuel Macron, the paper said, but no other politician could have saved the political order he inherited.
The protesters and the bond market are making opposite demands. Students and public-sector unions want more spending on schools and services. Buyers of French debt want proof that the deficit will shrink. The government cannot meet both demands with the same budget.
Part of a tracked trend
Energy-Shock Austerity Meets the Street in Europe
As expensive energy pushes up living costs, European governments trying to cut deficits will keep facing mass, sometimes violent protest. The unrest will water down consolidation plans and raise political risk premia on high-deficit sovereigns such as France, a pattern that recurs with each budget round.
Veracity: Corroborated
84/100- If true, who benefits
Marine Le Pen's National Rally gains politically if voters see a government that can satisfy neither the protesters nor bond buyers, and investors who are short French debt gain as the spread over German Bunds widens.
- The nuance
France 24 confirms the 70,000 deployment, and FXStreet confirms the yield passed 5% for the first time since 2002. The yield touched 5.002% and closed at 4.979%, the protesters' stated complaint is the cost of living and school conditions rather than the €54 billion package alone, and the government has authorized only union-organized marches on Saturday.
An open-source-intelligence read of how likely this story is true with its real nuance, not a judgment of any outlet. It assesses the claim, weighing independent and adversarial reporting. How we label confidence.
What this means
The risk passes from the street to the bond market through the budget. Every concession on the €54 billion package widens the deficit that investors are already charging 5% to finance. French banks, holders of French government bonds and the euro-area spread complex are exposed. The European Central Bank's bond-buying backstop (the Transmission Protection Instrument) is available only to countries that follow sound fiscal policies. If France abandons consolidation, it weakens its own claim on that support. The 2018 yellow-vest protests are the precedent. Weeks of violent demonstrations ended with about €10 billion in concessions from Macron, and fiscal targets slipped. The likelier outcome is that the government gives up parts of the savings package within weeks, and French 10-year yields stay near or above 5%. This depends on protests keeping their size through the budget votes. Passage of the budget intact, followed by a narrower gap over German yields, would prove this read wrong.
Synthesized from: Dawn · Financial Times World · Financial Times · Buenos Aires Times
Townsquare
Start a discussion in Townsquare.
More from this edition
- Brent Nears $117 as Washington Lends Crude From a Strategic Reserve at Its Lowest Level Since 1982
- Washington Reduces Staff at Gulf Embassies as Trump Threatens "Another Little Epic Fury" Against Iran
- Dow Falls 653 Points as Doubts About Artificial-Intelligence Spending Spread Beyond Tech Stocks
- Japan's Core Inflation Rises to 2.1%, Above the Bank of Japan's Target for the First Time in Nine Months
- Brazil Votes Sunday With Lula and Flávio Bolsonaro Tied at 50% in the Final Datafolha Poll
- US Waiver Lets Russian Diesel Back Onto World Markets as Former Executives Say Novatek Secretly Ran an Alaska Gas Project
- Gold Holds Near $4,030 and Bitcoin Near $81,000 as Oil Jumps 3%, While Silver Falls 1%
Comments
0No comments yet.