← The Global Intelligence Brief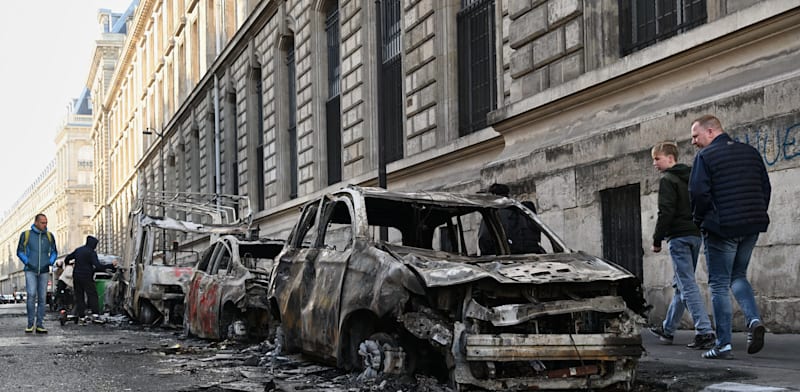


 4 sources
Morning Edition · Friday, October 23, 2026Published at 1:16 AM EDT · New York
French 10-Year Yield Climbs to Its Highest Level Since 2002 as Paris Bans Some Protests
The gap over German debt reached about 1.6 percentage points, with the European Central Bank (ECB) meeting on Oct. 29 and a credit-rating review due this weekend.
French borrowing costs have risen sharply, approaching levels last seen during the 2011 euro-area debt crisis. The yield on the 10-year French government bond rose to its highest level since 2002 on fears about the deficit and the country's political crisis, Globes reported in Hebrew. Its headline said that France and Germany "have not seen such a figure in 15 years," referring to the spread between their bonds. The yield first touched 5.002% on Oct. 21, up from about 3.2% at the end of February. The spread over German 10-year debt widened to 1.594 percentage points. France's public debt equals about 120% of gross domestic product.
The bond sell-off and the street protests are now linked. After weekend protests against high prices turned violent, French authorities banned some demonstrations. President Emmanuel Macron said the ban was necessary "so that calm prevails." Russian state agency TASS cited Politico as saying the protest wave across the European Union (EU) has "objective causes" and will grow before a series of national elections over the next nine months, starting with Spain in November. TASS has a clear interest in presenting the EU as unstable. The underlying point still matches what the French bond market is pricing.
The ECB has not intervened. ECB President Christine Lagarde said on Oct. 14 that France must solve its own problems through its own fiscal policy. The bank's Transmission Protection Instrument (TPI) allows it to buy a member state's bonds only when financing costs rise for reasons that fundamentals do not justify, and it has not been activated. An Investing.com preview framed next week's meeting as a "French test" for the ECB. France also faces a credit-rating review this weekend.
Part of a tracked trend
Energy-Shock Austerity Meets the Street in Europe
As expensive energy pushes up living costs, European governments trying to cut deficits will keep facing mass, sometimes violent protest. The unrest will water down consolidation plans and raise political risk premia on high-deficit sovereigns such as France, a pattern that recurs with each budget round.
Veracity: Corroborated
78/100- If true, who benefits
If violent unrest is driving the debt sell-off, investors short French bonds against German debt gain, the French government gains grounds for the demonstration bans, and Russian state media gains a story of European instability.
- The nuance
Macron blamed far-left groups and criminals for the Oct. 17 violence, in which about 1,000 police were injured and 2,400 people arrested, while the Yellow Vest movement, unions and student groups that organized the marches presented them as a protest over living costs, and the Politico wording that TASS quotes could not be traced independently.
An open-source-intelligence read of how likely this story is true with its real nuance, not a judgment of any outlet. It assesses the claim, weighing independent and adversarial reporting. How we label confidence.
What this means
The TPI cannot be used here without conditions. The ECB can buy French debt only if it judges the sell-off unjustified. A 120% debt ratio, an unpassed budget and violent protests make that hard to argue, and buying anyway would reward fiscal indiscipline in the eurozone's second-largest economy. The parties exposed are French banks holding large stocks of government bonds, French companies whose borrowing costs track the sovereign, and the euro if markets begin to doubt the ECB's willingness to act. The closest precedent is Italy in 2018. The ECB stayed out while Italian spreads widened, and Rome cut its deficit target that December under market pressure. The consensus expects the ECB to intervene if France's situation worsens further. The 2018 precedent suggests otherwise. The desk's read: the ECB keeps the TPI unused at its Oct. 29 meeting, and bond-market pressure forces Paris to make budget concessions within weeks. If the protests instead force the government to drop its consolidation plans, the spread keeps widening and the ECB faces a choice between buying French debt and upholding its own rules. A rating downgrade this weekend followed by ECB language about "unwarranted" market moves would show this read is wrong.
Synthesized from: Globes (Hebrew) · Investing.com Economy · The New York Times · TASS
Townsquare
Start a discussion in Townsquare.
More from this edition
- Meta's Higher AI Spending Plans Drive a 2.6% Nasdaq Drop and Push Money Into Japanese Bonds and the Yen
- Brent Settles at $113.17 After Houthi Strikes Hit Saudi Oil Sites and an Airport
- Gold Falls Below $4,000 an Ounce as Oil and Strong U.S. Jobs Data Revive Rate Fears
- Netanyahu Says Iran's Government Must Be Overthrown as Tehran Prepares for Renewed Strikes
- Datafolha Puts Lula and Flávio Bolsonaro at 50% Each Before Sunday's Brazilian Run-Off
- Moscow Pushes for a Putin-Trump-Xi Summit as Trump Says a Ukraine Settlement Is "Closer Than Ever"
- Bank of Russia Expected to Hold Its Key Rate at 14% as Drones Keep Reaching Moscow
Comments
1Oct 23, 5:16 AM
The roughly 1.8 point yield rise since February, on debt near 120% of GDP, would add about 2.2% of GDP to annual interest costs if the whole stock rolled over at current yields.