← The Global Intelligence Brief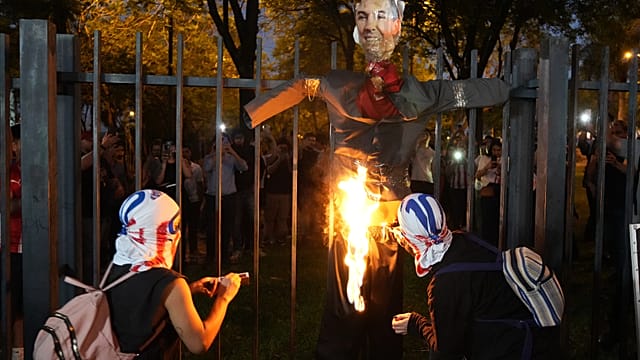


 4 sources
Morning Edition · Friday, November 6, 2026Published at 4:38 AM EST · New York
Ueno Bank's collapse freezes the savings of about 3 million Paraguayans and forces out the central bank chief
President Santiago Peña offered to resign and now faces a Senate impeachment trial, while depositors wait on a guarantee capped at about $38,000 each and the state has roughly $869 million trapped in the bank.
On November 3 the Central Bank of Paraguay (BCP) took control of Ueno Bank after its solvency ratio fell below half the legal minimum. The takeover froze the savings of about 3 million customers and more than $800 million in public funds. The digital lender held more than $2.8 billion in deposits, and its app and cards stopped working. Africanews reports that nearly half the population has lost access to its savings, and thousands of people have protested in the streets.
The deposit guarantee fund covers up to 75 minimum wages per depositor per institution, about 228.3 million guaraníes or roughly $38,000. The central bank has promised only "the greatest possible protection" above that cap. The resolution procedure allows up to 15 days to start repayments. Paraguay's bankers' association, Asoban, says the failure is isolated and that Ueno held about 7% to 8% of system deposits.
The political crisis has moved faster than the repayments. The Guardian reports that Peña's government had authorized Ueno to expand its operations sharply before it collapsed. Peña once held a stake in Ueno's parent company and sold it in 2025. NBC News reports that eight senior Ueno executives, including founder Miguel Vázquez, have been detained, and that central bank president Carlos Carvallo has resigned. Peña tendered his resignation on Thursday. According to MercoPress, Congress lacked a quorum to consider the resignation, which leaves him formally in office. He says he will defend himself before the Senate. Argentina has denied reports that he entered its territory.
Outlets frame the cause differently. Venezuela-based teleSUR calls Ueno the bank tied to Peña and to "Milei's model for the region," and reports that government deposits made up about 29% of its funding at the end of June. That figure supports a different reading as well. A lender that drew close to a third of its funding from the state, expanded with regulatory approval, and was overseen by a central bank chief with prior ties to it was not built through open competition. It was a politically directed allocation of credit.
Part of a tracked trend
Politically Connected Bank Failures in Latin America
Fast-growing Latin American lenders that rely on state deposits and regulatory favor will keep failing in ways that freeze uninsured savings and topple officials, raising the cost of holding large balances in local banks and pushing savers toward dollars and offshore accounts.
Veracity: Corroborated
78/100- If true, who benefits
If state deposits and regulatory approval fueled Ueno's growth, President Santiago Peña's opponents in Congress and regional critics of the Milei-aligned economic model gain, while the state pension and health fund, the Instituto de Previsión Social (IPS), waits on about $380 million it says it has in the bank.
- The nuance
The edition says Peña held a stake in Ueno's parent, but the bank says he was never a shareholder and describes him as a business partner of Grupo Vázquez until March 2025, a Ueno executive has put public money below 15% of deposits against the 29% figure teleSUR reports, and the edition's "politically directed credit" conclusion is an inference, not a finding by prosecutors.
An open-source-intelligence read of how likely this story is true with its real nuance, not a judgment of any outlet. It assesses the claim, weighing independent and adversarial reporting. How we label confidence.
Synthesized from: The Guardian · Africanews · MercoPress · teleSUR
Townsquare
Start a discussion in Townsquare.
More from this edition
- Asian chip stocks follow the Nasdaq down as investors bet Democratic gains will slow data-center building
- Bank of England raises Bank Rate to 4%, its first increase since 2023, and warns more rises are likely
- Brent climbs back toward $100 after new Hormuz tanker attacks but heads for a weekly loss of about 12%
- Washington weighs resuming strikes on Iran on November 9, Fox News reports, as Riyadh denies a $51 billion Houthi demand
- Goldman Sachs cuts its year-end gold forecast to $4,150 as Fed officials argue for more rate increases
- Bitcoin falls to about $75,600 as more than $1 billion in leveraged positions are liquidated
- Luxembourg court rules a Russian firm's securities were wrongly kept frozen as Britain holds an Indian captain over a Russian oil cargo
Comments
1Nov 6, 9:38 AM · edited
With $2.8 billion spread over about 3 million customers, the average balance is near $930, so the $38,000 cap mainly matters for large accounts and the state's $869 million, about 31% of deposits.